Sansone CPA & Financial brings fee-only wealth management and tax planning under one roof, for Algonquin business owners, families, and pre-retirees who are tired of fragmented advice.
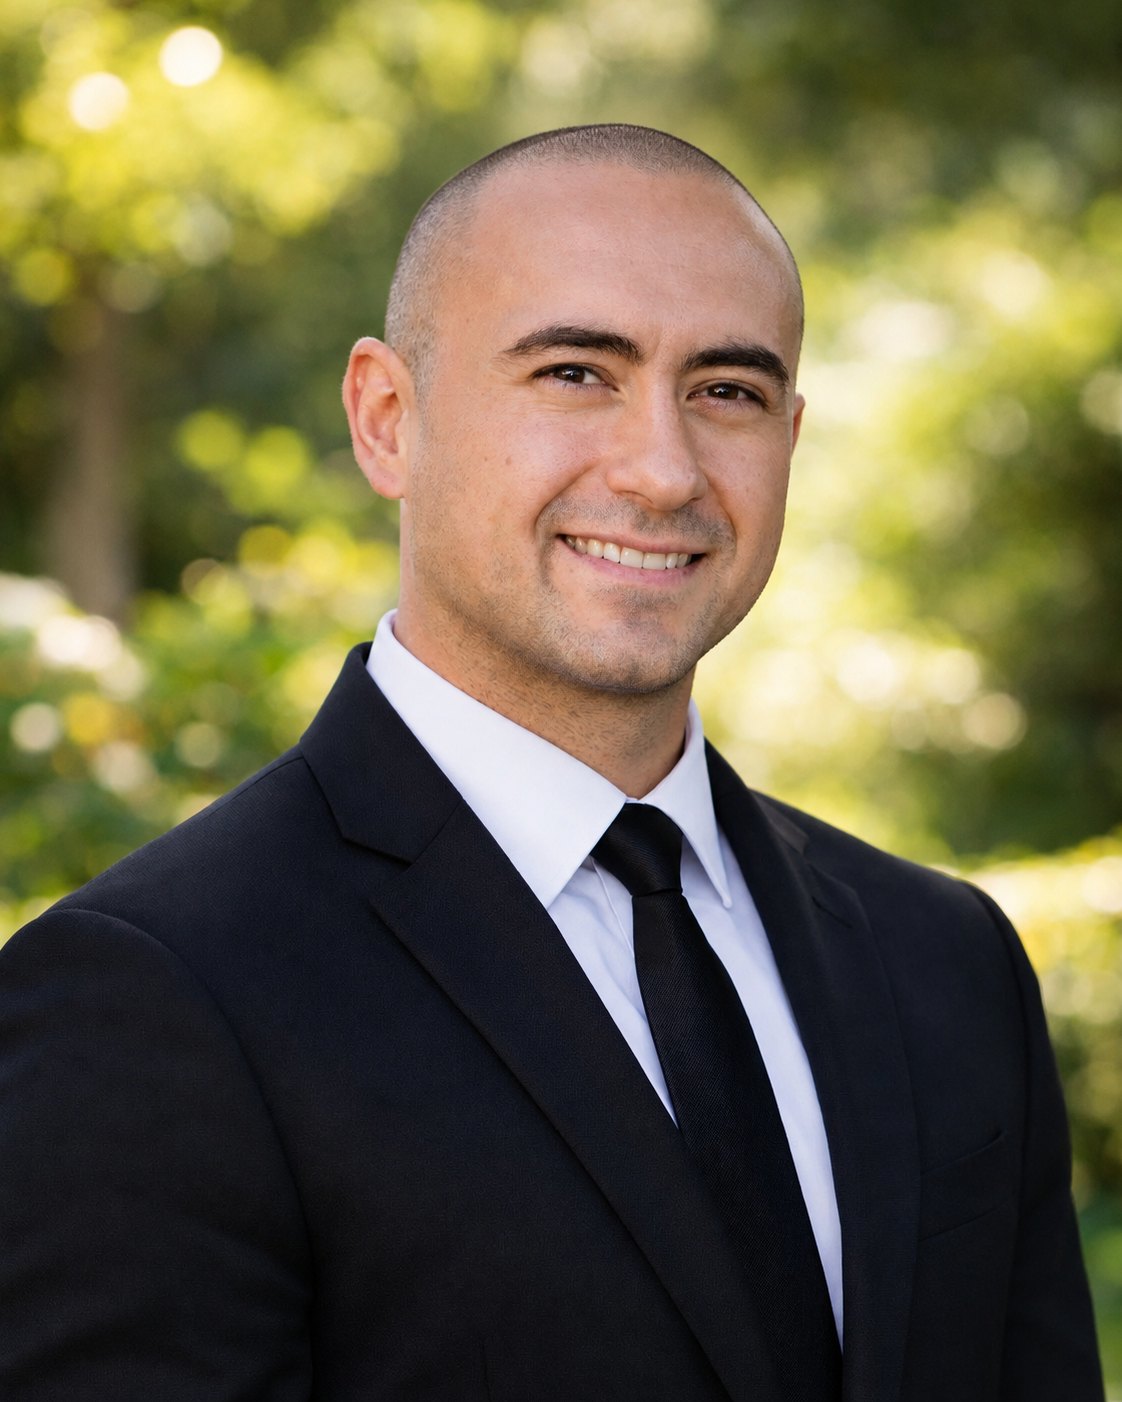
Financial & Tax Advisor
Anton specializes in retirement planning, business tax strategy, and personalized financial advice designed to reduce taxes and support long-term financial goals. Whether you’re a solo entrepreneur, a growing practice, or planning for life after work, he delivers clear, actionable guidance tailored to your situation.
Most advisors specialize in either taxes or investments. Anton holds the credentials and the responsibility for both, which is what lets Sansone coordinate the two sides of your financial life under a single strategy.
“If your CPA and your advisor don’t talk to each other, you’re paying for two opinions that might contradict each other. I’d rather give you one full opinion.”
Anton Prokopenko, MBA, CPA, CFP®, EA
Between the Randall Road corridor and the older downtown along the Fox River, Algonquin has plenty of owner-run businesses. For an owner, the business tax return and the household tax return are really one plan, and most of the expensive mistakes happen where the two meet.
Paying yourself from an S corporation. If you work in your S corporation, you need to take a reasonable W-2 wage through payroll before taking distributions. Moving money from the business account to your personal account isn’t payroll, and a wage that’s too low is a common audit issue.
Choosing a retirement plan. A SEP-IRA, a solo 401(k), and a 401(k) with employees each fit a different owner. The right one depends on your wages, whether you have staff, and how much you want to save, and the contribution reduces taxable business income.
Estimated taxes. Owners don’t have withholding doing the work for them. A fall tax projection sets your fourth-quarter estimate so April doesn’t bring a surprise or an underpayment penalty.
A hypothetical example: an owner with no employees runs an S corporation and pays herself a modest wage. Raising the wage increases payroll tax, but it also raises how much the business can contribute to her 401(k). We set the wage and the retirement plan together, because each one changes the other.
We handle your business tax return, your personal tax return, and your investments in one relationship. See our planning for business owners.
Based in Crystal Lake, working with clients across McHenry County and northern Kane County, in person at our Crystal Lake office or virtually.
Q.01
Our office is at 850 S McHenry Ave, Suite D, in Crystal Lake, about 10 to 15 minutes from downtown Algonquin. Take Pyott Road north to Rakow Road, then McHenry Avenue. From the Randall Road side, take Randall north to McHenry Avenue. Virtual meetings are available too.
Q.02
For an S corporation, no. That transfer is a distribution, and owners who work in the business also need a reasonable W-2 wage run through payroll. For a sole proprietorship or single-member LLC taxed as one, a transfer is simply a draw, and you’re taxed on the business profit either way.
Q.03
It depends on your wages, whether you have employees, and how much you want to save. A SEP-IRA is simple, a solo 401(k) usually allows more for an owner with no staff, and a 401(k) for a team adds rules about covering employees. Set-up deadlines differ, so start the conversation before year-end.
Q.04
Not always. A single-member LLC is usually reported on your personal tax return unless you elect S corporation treatment. An LLC with two or more owners files a partnership tax return by default.
Q.05
When the payroll tax savings outweigh the added costs: running payroll, filing a separate business tax return, and paying yourself a reasonable wage. There is no single profit number that works for everyone, so we run both versions before you elect.
A free 30-minute call. No prep needed, just bring your questions.